
Debt Consolidation vs. Refinancing: Which is Right for You?
Managing finances can be challenging, especially when it comes to handling multiple debts. Two popular strategies to tackle this issue are debt consolidation and refinancing. Each approach offers unique benefits and may be suitable for different financial situations. Understanding the differences between these options can help you make an informed decision.
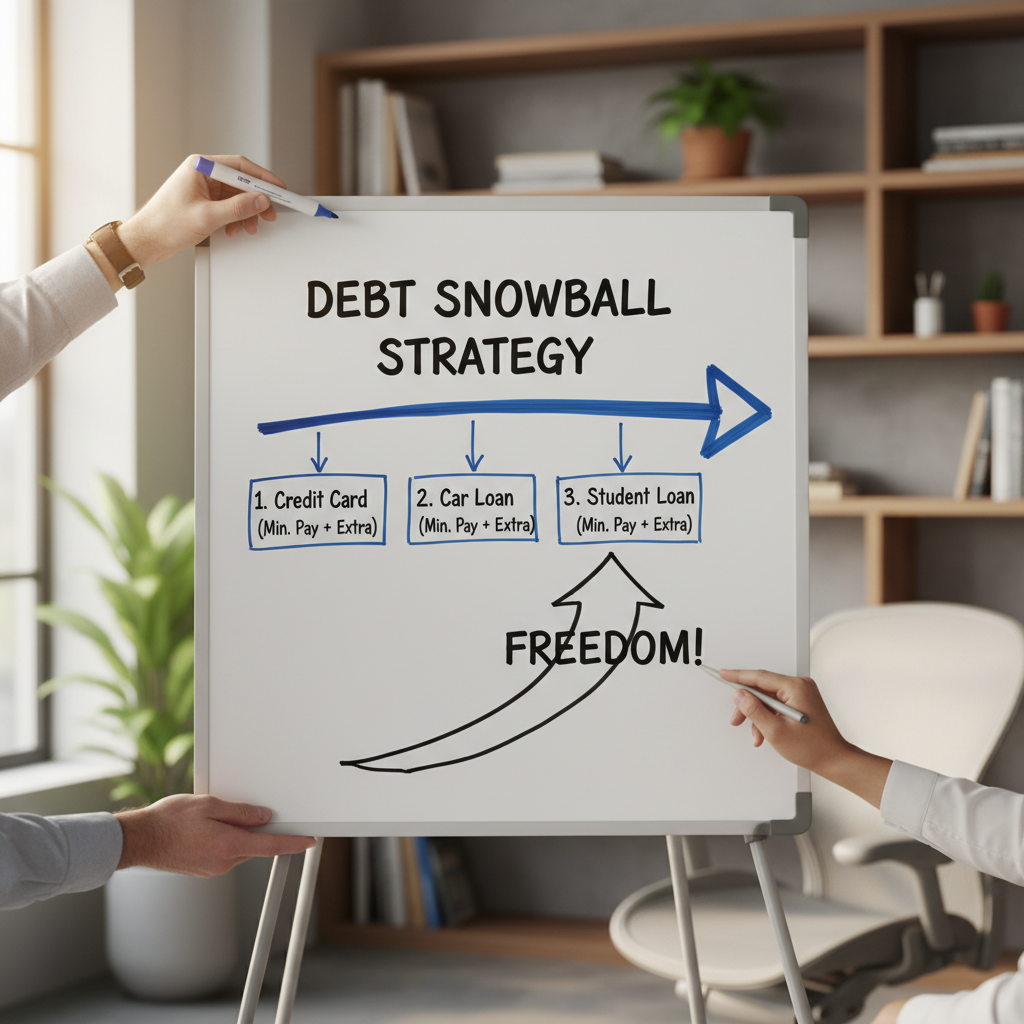
Understanding Debt Consolidation
Debt consolidation involves combining multiple debts into a single loan with a fixed interest rate. This method can simplify payments by reducing the number of creditors you owe. Typically, debt consolidation is used for credit card debts, personal loans, and other unsecured debts.
Benefits of Debt Consolidation
The primary advantage of debt consolidation is the ease of managing a single monthly payment. This can help reduce stress and improve your financial management. Additionally, if you secure a lower interest rate, you might save money over time.
However, it’s important to be cautious. Consolidating your debts may extend the repayment period, potentially leading to paying more in interest over the life of the loan. Ensure you evaluate the total cost before proceeding.
Exploring Refinancing
Refinancing involves replacing an existing loan with a new one, usually to obtain better terms. This option is commonly used for mortgages, auto loans, and student loans. By refinancing, you might secure a lower interest rate or adjust the loan term to better fit your financial needs.
Advantages of Refinancing
The main benefit of refinancing is the potential to reduce your monthly payments and save on interest. If your credit score has improved or market rates have decreased since you took out the original loan, refinancing could be a wise choice.
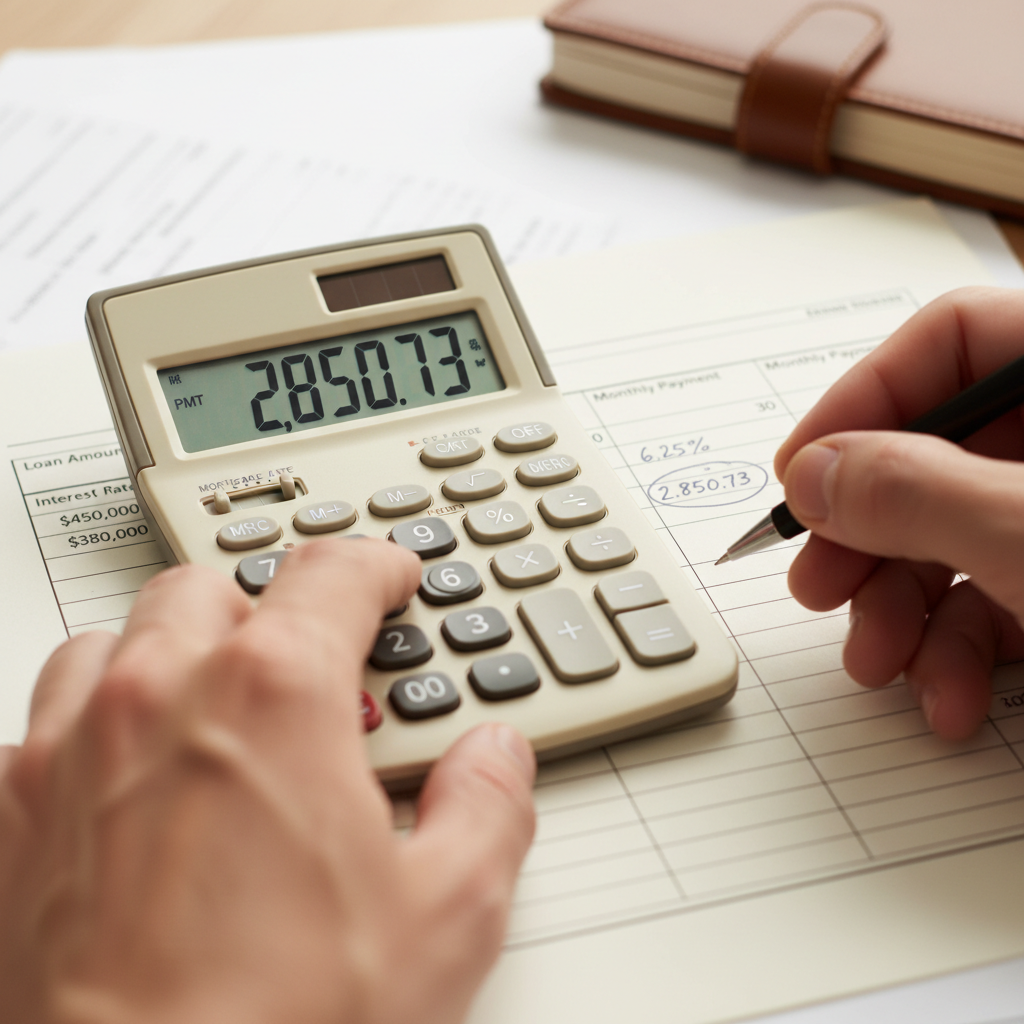
However, be aware of any fees associated with refinancing, such as origination fees or prepayment penalties. It’s crucial to calculate whether the savings outweigh these costs.
Which Option is Right for You?
Choosing between debt consolidation and refinancing depends largely on your individual financial situation. Consider the following factors:
- Type of debt: Consolidation is often ideal for multiple unsecured debts, while refinancing suits specific loans like mortgages.
- Interest rates: Compare current rates to see if refinancing offers a significant advantage.
- Repayment goals: Decide whether you want to lower monthly payments or pay off debt faster.
In some cases, a combination of both strategies might be the best approach. Consulting with a financial advisor can provide personalized guidance tailored to your circumstances.
Ultimately, both debt consolidation and refinancing can be effective tools for managing debt. By understanding their differences and benefits, you can make a choice that aligns with your financial goals.